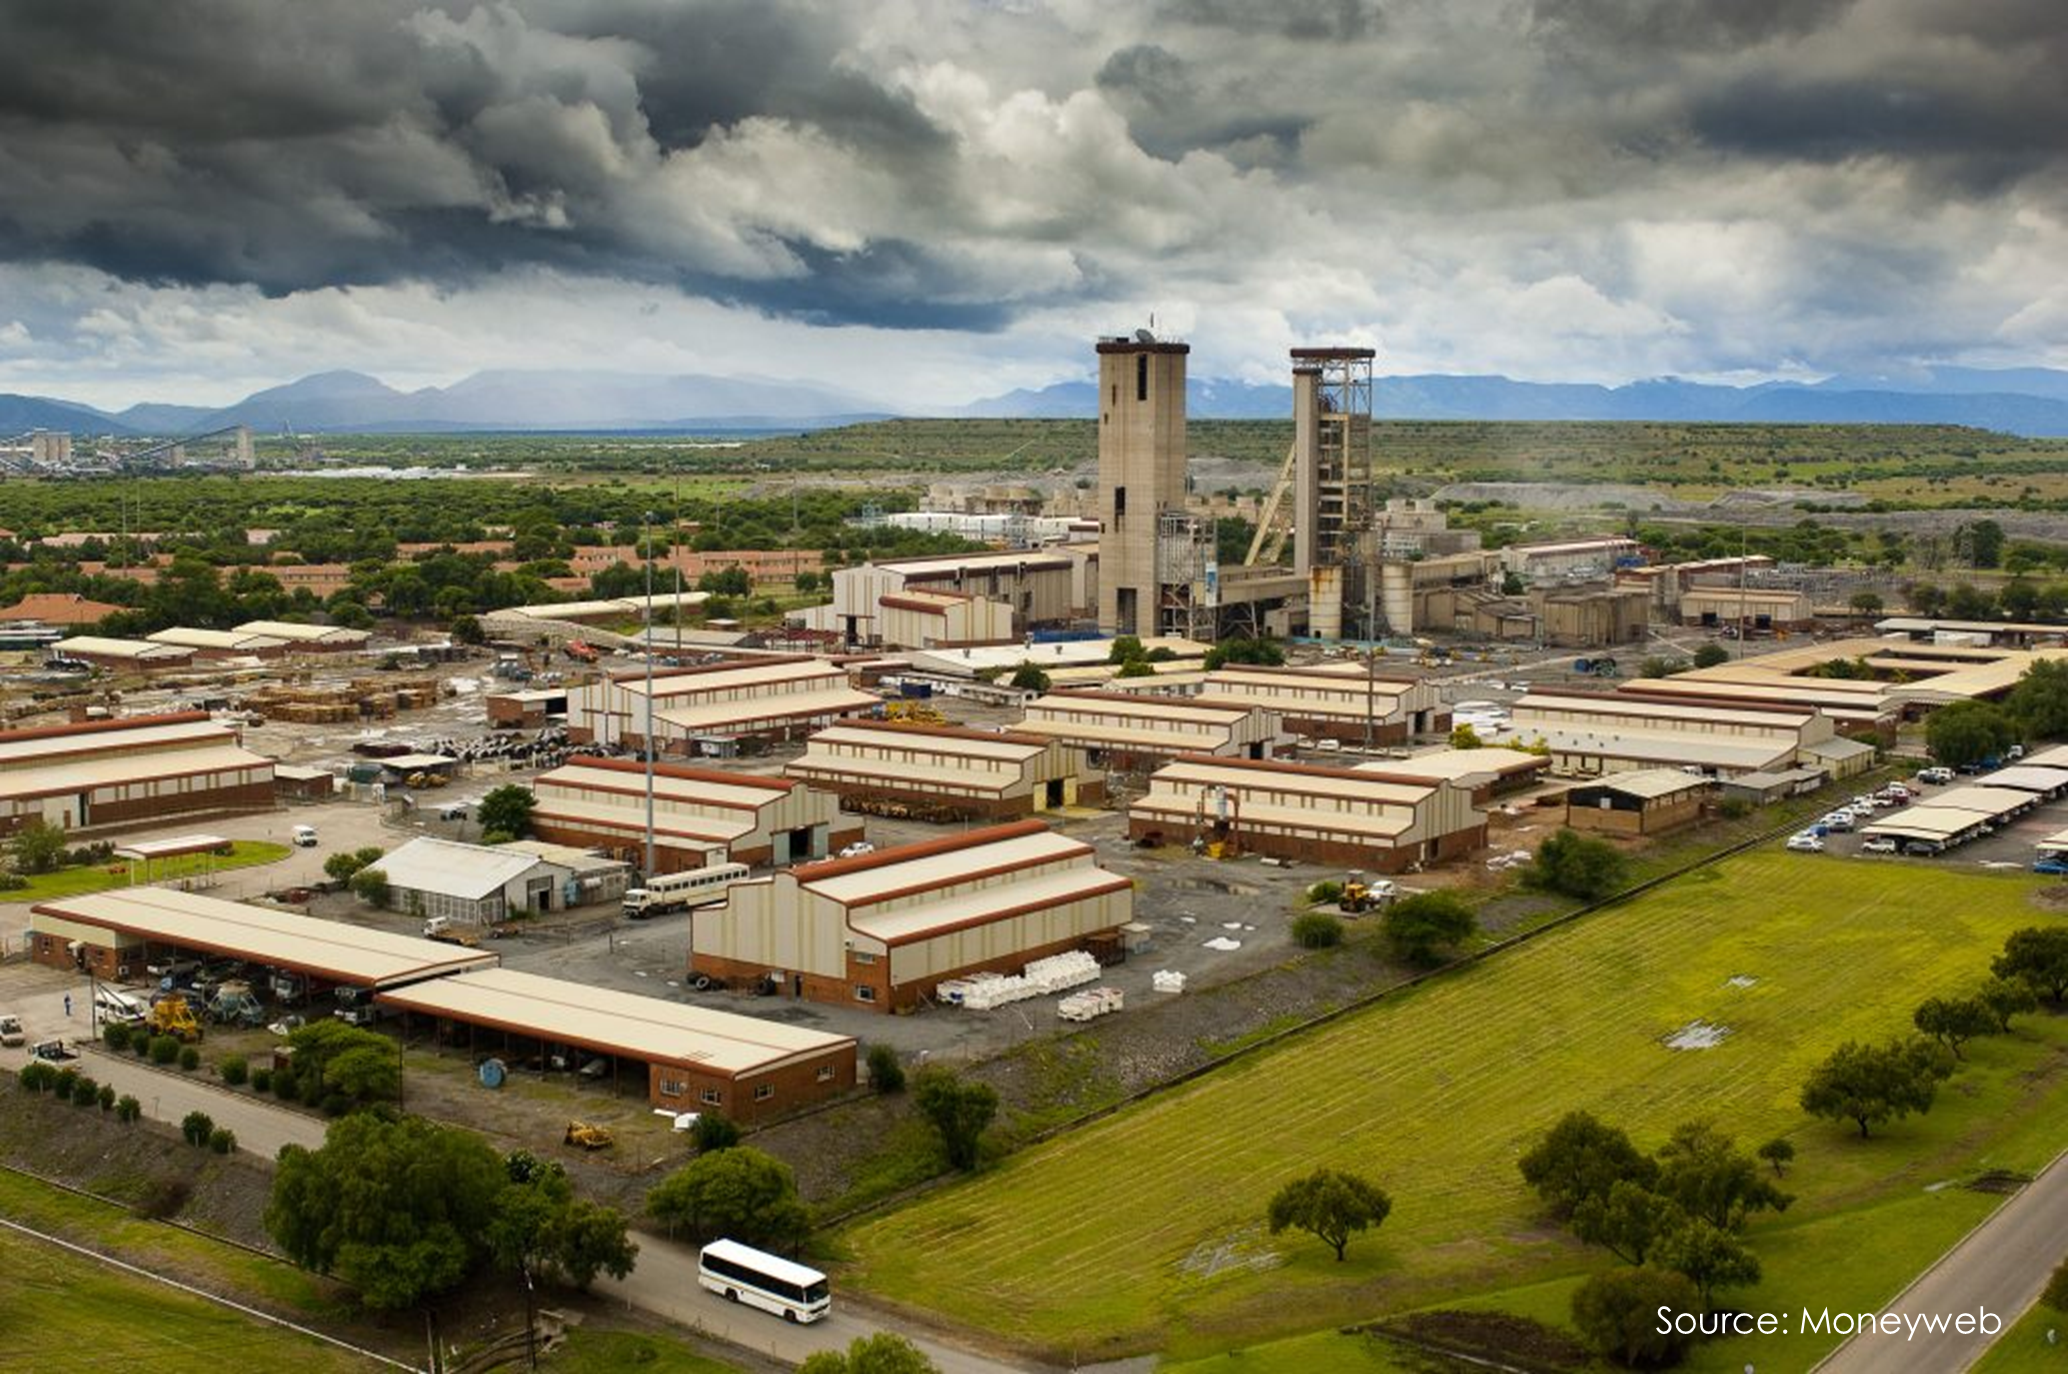
| Imagery Source: Moneyweb |
| Information Source: JSE SENS |
| Northam Holdings’ financial results for the year ended 30 June 2025 (“F2025”) are underpinned by a solid operational performance. Notwithstanding this, Northam Holdings expects to report a decrease in basic and headline earnings per share for F2025 compared to the financial year ended 30 June 2024 (“F2024”). |
| Key metrics for F2025 |
- The group’s equivalent refined metal produced from its operations increased to 899 244 oz 4E (F2024: 892 876 oz 4E).
|
- Group production of chrome concentrate increased by 9.0% to 1,439,752 tonnes (F2024: 1,320,963 tonnes), on the back of improvements in UG2 tonnage throughput, feed grades and concentrator yields.
|
- 5.2% increase in total refined metal produced to 937 942 oz 4E (F2024: 891 721 oz 4E).
|
- 6.9% increase in sales revenue to R32.9 billion (F2024: R30.8 billion), primarily attributable to a 5.9% increase in total metal sold to 1 006 475 oz 4E (F2024: 950 251 oz 4E), with total metal sold by the group having exceeded 1 million oz 4E for the first time.
|
- 8.1% increase in group unit cash cost per equivalent refined 4E ounce to R25 728/4E oz (F2024: R23 811/4E oz), reflecting the impact of mining cost inflation.
|
- 25.5% decrease in operating profit to R3.6 billion (F2024: R4.8 billion), reflecting the impact of mining cost inflation against flat rand metal prices.
|
- 14.8% – 19.8% expected decrease in basic earnings per share.
|
- 9.4% – 19.4% expected decrease in headline earnings per share.
|
- Net debt of R5.1 billion with a net debt to EBITDA ratio of 1.04 at year-end, before taking into account the post-year-end USD66.0 million once-off cash inflow referred to below.
|
- R12.3 billion fully undrawn and available bank facilities.
|
| Financial results |
| Sales revenue increased by 6.9%, against an increase in cost of sales of 13.0%. This resulted in an operating profit of R3.6 billion (F2024: R4.8 billion), and an operating profit margin of 10.9% (F2024: 15.7%). |
| We operate a largely fixed cost business and consider increasing production, and doing so efficiently and sustainably, to be our best defence against current global inflationary pressures and weak metal prices. Our capital allocation and treasury decisions have been guided by our growth strategy, and our results have benefited from our consistent approach to growing our production base down the sector cost curve. |
| Earnings before interest, taxation, depreciation and amortisation (“EBITDA”) amounted to R4.9 billion (F2024: R6.3 billion). |
| Metal inventory on hand increased to 495,350 oz 4E, with a carrying value of R9.0 billion and a sales value of R16.5 billion when applying the 4E basket price and exchange rate as at 30 June 2025. |
| Our operations generated cash to the value of R4.7 billion, before cash capital expenditure of R5.0 billion. |
| During F2025, Domestic Medium Term Notes (“DMTNs”) amounting to R4.2 billion were settled upon maturity. In June 2025, Northam successfully concluded a private placement of new DMTNs to the value of R5.7 billion under Northam Platinum’s R15.0 billion DMTN Programme, as amended and/or supplemented from time to time (“DMTN Programme”), (“Placement”). The maturity profile of the new notes has been staggered intentionally, taking into consideration, inter alia, Northam’s business strategy, the extent and expected completion dates of current and planned capital projects and the maturity profile of the notes in issue under the DMTN Programme before the Placement. This provides additional certainty and flexibility, and protects Northam’s liquidity position and capacity to execute growth projects through metal price cycles. |
| Our growth strategy and allocation of capital are underpinned by our belief in the special metals we produce and their continued global importance. The Placement will provide Northam with sufficient flexibility and liquidity to pursue an accelerated capital investment programme in the short- to medium-term in the continued execution of our strategy to safely, efficiently and sustainably increase our PGM production against a depleting primary supply from the sector. The solid operational performance, together with our favourable position on the sector cost curve, ensures Northam’s sustainable future, enhancing our investment case. |
| As at 30 June 2025, the group’s gross cash balance amounted to R6.9 billion. |
| Northam’s total available banking facilities amount to R12.3 billion, comprising the revolving credit facility (“RCF”) of R11.3 billion and general banking facilities (“GBF”) of R1.0 billion. Both these facilities remain undrawn. |
| Post year-end, once-off cash inflow of USD66.0 million |
| After year-end, Northam and Heraeus Precious Metals GmbH & Co. KG (“Heraeus”) concluded an amicable engagement undertaken to arrive at a mutually acceptable redetermination of historical refining outcomes, spanning over multiple years, to more accurately and fairly reflect refining results. Heraeus has made a once-off payment to Northam, to the value of USD66.0 million, in this regard. Going forward, Heraeus has implemented certain proactive steps to ensure a more accurate and fair determination of refining outcomes. |
| Capital expenditure |
| Capital expenditure of R4.9 billion related to significant activity on the Western extension project at Zondereinde, the ongoing ramp-up at Eland, mining fleet purchases and concentrator upgrades at Booysendal South. Further development activity at Zondereinde and Eland is planned for the 2026 financial year (“F2026”). |
| At Zondereinde mine, stoping continues to ramp up within the Western extension section. Equipping of 3 shafts for personnel and material transport, as well as the provision of services, is in progress, with the establishment of the intermediate pumping chamber achieving a key milestone. Reaming of 3a ventilation shaft continues. Both shafts are scheduled for commissioning during the first quarter of the 2026 calendar year. These milestones will deliver efficiency benefits to mining in the Western extension section. Pilot drilling of the 3b rock hoisting shaft is complete, and reaming will soon commence. |
| At the group’s metallurgical facilities, upgrades to the base metal removal plant are progressing well and the expanded and upgraded furnace slag concentrator is processing slag inventory. Following a scheduled rebuild completed during August 2024, smelter furnace 2 is operating well, as is furnace 1. |
| At Booysendal, all mining modules are operating at steady state levels. Declining development is continuing to increase mineable reserves and operational flexibility. |
| At Eland mine, processing of ore from surface sources continues, whilst ore production from underground mining ramps up, albeit at a reduced rate as a result of additional safety interventions. This, combined with an increase in stoping crews operating in advance of production, negatively impacted unit cash costs, a situation that is expected to normalise over the next two years. Development of the decline system was recommenced following a temporary pause in 2024, as part of a capital trimming exercise at the time for liquidity preservation purposes. A planned reconfiguration of the mine’s ventilation circuit towards the end of F2025 has enabled multi-blast conditions, which now allow for accelerated decline development rates. A new 4.5 metre diameter raise-bored ventilation shaft significantly improved environmental conditions, particularly in the deeper sections of the mine that are critical to the medium-term ramp-up, and facilitated the planned ventilation reconfiguration. Focus remains on strike and raise development, to increase mineable reserves. Underground stoping ramp-up continues, improving feed volumes and grades to the concentrator. |
| Enhancements to the PGM and chrome concentrator circuits at each of the mines are continuing to generate low-risk and profitable improvements in metal recoveries. |
| Capital expenditure for F2026 is estimated at R5.2 billion, with the bulk to be invested in elective growth programmes. |
| The possibility of further Eskom load curtailment events and newly emerging challenges from water utilities caused by failing infrastructure could lead to operational disruptions. The combination of additional on-demand self-generation capacity at all our operations, together with ongoing improvements in water recycling and supplementary water supplies, mitigates these significant risks. |
| To reduce the impact of Eskom tariff inflation and to further our decarbonisation strategy, the group is pursuing a series of renewable energy initiatives. |
| The development of an 80 MW solar power facility at Zondereinde is in progress. Development is in collaboration with an independent power producer (“IPP”) through a power purchase agreement (“PPA”). Power will be supplied behind the Eskom meter and will thus not be subject to load curtailment events. Construction has commenced, and commissioning is scheduled midway through F2026. Once operational, the facility will improve the security of power supply, whilst reducing energy costs and the mine’s carbon footprint. The group will further benefit from two additional PPAs concluded with IPPs. Firstly, for 140 MW of renewable energy from the Karreebosch wind farm, located close to Sutherland in the Western Cape, a project that is under construction and scheduled to generate energy from 2027, and secondly, 80 MW from the Thakadu solar farm, located close to Virginia in the Free State, also scheduled for commissioning in 2027. The group is also exploring other renewable energy projects, and we expect the bulk of our energy requirements to be met from renewable sources before the end of the decade. |
| Conclusion |
| Commodity markets are known for their cyclicality. The current outlook for global PGM demand and supply remains uncertain, which in turn results in an uncertain outlook for PGM prices. A raft of global geopolitical and macro-economic issues has the potential to cause further disruption to the PGM markets and metal prices, whilst the possibility of Eskom load curtailment events and interruptions in water supply could lead to additional operational disruption and challenges. We continue to monitor the market and are confident that our recently commissioned, additional on-demand self-generation capacity units at all our operations will significantly contribute towards mitigating risks associated with load curtailment events, in addition to the ongoing efforts and initiatives to increase water recycling and the availability of supplementary water supplies. |
| Despite the increase in PGM prices after year-end, the low PGM price environment is constraining earnings across the entire PGM sector. The sector’s ability to respond to lower PGM prices by suspending or reducing costs is limited, as the majority of mining costs are fixed in nature. This is consequently constraining cash generation across the sector, requiring ever more prudent management of liquidity. |
| The following factors have been considered as part of the liquidity management of the group: |
- The group’s growth strategy is focused on growing sustainable production down the sector cost curve by developing shallow, mechanisable orebodies. Our programme of optimising existing operations continues and remains on track. We have utilised our balance sheet to grow the business, and the project pipeline has been funded through cash generated by our operations, as well as the utilisation of our DMTN Programme and, from time to time, our banking facilities.
|
- The staggered maturity profile of Northam’s DMTN Programme provides an additional degree of certainty and flexibility to enable prudent cash flow and liquidity management. Northam has proactively managed its DMTN Programme’s maturity profile to appropriately match the production growth build-up, and therefore the expected cash generation capacity of the group. Furthermore, the maturity profile has been staggered over a number of years to enhance and protect our liquidity position through metal price cycles.
|
- The group’s available banking facilities amount to R12.3 billion, comprising an R11.3 billion RCF and a R1.0 billion GBF. These facilities remain fully undrawn.
|
- Should market conditions require, adjustments will be made to the group’s expansionary capital expenditure, if necessary, to preserve liquidity.
|
| In light of prevailing PGM market uncertainty, Northam remains internally focused with full emphasis on operational excellence, particularly surrounding safe, sustainable production and efficient mining at the right cost. |
| Despite recent improvements in metal prices being realised, the global economic outlook remains uncertain, with potentially volatile metal markets and exchange rates. |
| Northam’s relative position in the industry and the ability to retain operational flexibility and balance sheet strength remain our key differentiators. The group remains committed to the strategic goal of growing safe and sustainable production down the sector cost curve. |
| The financial information contained in this announcement is the responsibility of the board of directors of Northam Holdings and has not been reviewed or reported on by Northam Holdings’ auditors, PricewaterhouseCoopers Incorporated. The audited results of Northam Holdings for F2025 are expected to be published on or about 29 August 2025. |
| For the full document, click the link below |
| Northam Platinum Limited |
| Stay ahead of the curve! Subscribe to InsidEntity for daily updates on all your favourite companies. |