| Imagery Source: JD Sports Fashion PLC |
| Information Source: JD Sports Fashion PLC |
| Focused execution against our strategic objectives;
announcing further £100m share buyback |
| Headlines: |
- Improved LFL sales trend for Q2 in North America; Europe & UK affected by tough prior year comparatives due to the Euro 2024 tournament
|
- Good performance in apparel; footwear is softer, given the end of the cycle for key product lines
|
- Maintaining trading disciplines with controlled price investments, particularly in online
|
- Strong progress against strategic objectives across omnichannel customer proposition, store footprint, supply chain and North America operations. Costs and cash are well controlled.
|
- Expect to be in line with current market expectations(2,3) for FY26 profit before tax and adjusting items (PBTAI), albeit we continue to assess potential impacts from the US tariff.s
|
- Announcing today a new £100m share buyback programme, reflecting confidence in medium-term industry growth, our ongoing market share gains and focused execution
|
| Régis Schultz, CEO of JD Sports Fashion plc: |
| "We are making strong progress in developing our omnichannel customer proposition, store footprint and supply chain, and we are controlling our costs and cash effectively. I am proud of all our teams across the globe for their energy and focus against tough trading conditions. |
| "For Q2, in North America, we saw an improved performance following the deferral of several product launches from Q1, along with stronger sales trends in apparel and online. In both Europe and the UK, we were annualising tough comparators from the Euros football tournament last year, but still saw a good underlying performance in apparel and from newer footwear lines. |
| "Across our regions and fascias, in general, we see a resilient consumer, albeit very selective in their purchases. We therefore remain cautious on the trading environment going into H2. For our FY26 profit before tax and adjusting items, we expect to be in line with current market expectations, before any indirect impact of US tariffs, which we continue to work through. |
| "We are well placed to continue growing our market share in the key growth regions of North America and Europe, and confident about the medium-term growth prospects for our industry. Reflecting this, we are reaffirming our commitment to enhanced shareholder returns, and announcing today a new £100m share buyback following the successful completion of the first £100m programme last month." |
| Strong and focused execution against strategic objectives: |
- North American operations: (i) DTLR and Shoe Palace took over the operations of 198 City Gear stores on 1 June; (ii) our new JD/Finish Line e-commerce platform went live in H1; and (iii) Shoe Palace's Morgan Hill distribution centre (west coast of the US) went live in May, with JD/Finish Line planning to go live at the end of this year. This will make Morgan Hill the JD Group's first multi-fascia distribution centre, unlocking significant improvements in speed to store replenishment and online fulfilment. nt
|
- European supply chain: JD Group's Heerlen distribution centre (The Netherlands) continues to ramp up, and is on track to launch automation this year (for stores, with online to follow in H1 next year)
|
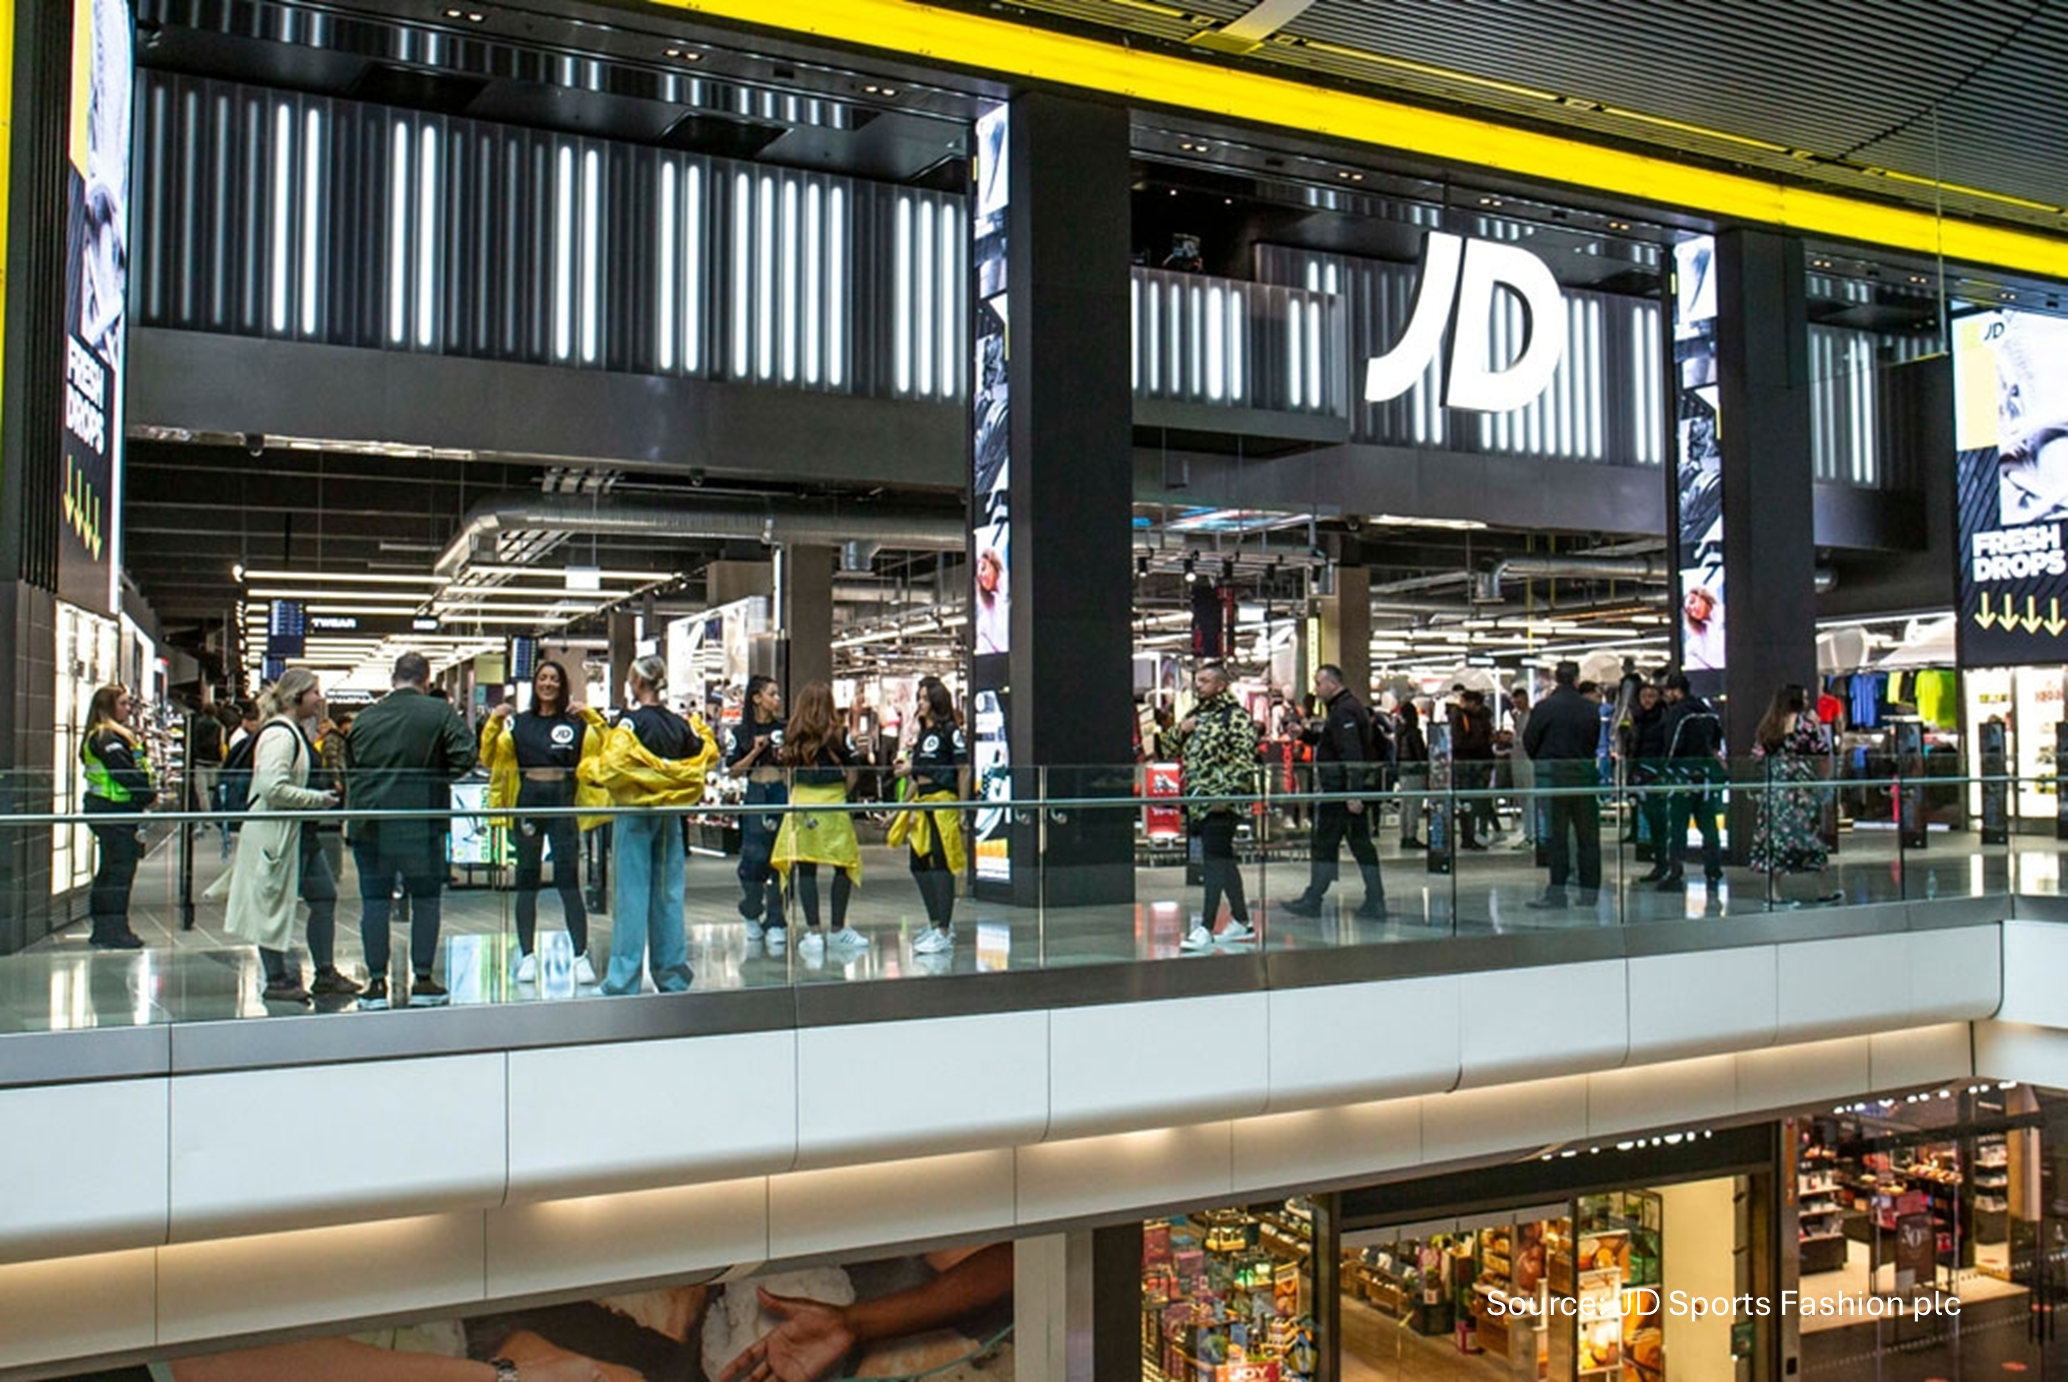
- Focused JD fascia store openings: In H1, we opened new JD fascia flagship stores in the UK (Trafford Centre, Manchester), North America (Las Vegas and Vancouver) and Asia Pacific (Melbourne), with positive early learnings and strong results in particular from the Trafford Centre store. Also in the period, in North America, we saw the conversion of 22 Finish Line stores into JD fascia stores. Global JD LFL -3.0% and organic sales growth +3.7%, with +42 net new JD stores (driven by North America and Europe)
|
| Q2 Performance highlights: |
| North America (36% of Q2 sales) |
- Resilient performance led by JD and DTLR fascias, against strong Q2 comparatives
|
- Good performance in newer footwear lines (following a shift in the product launch schedule from Q1, as previously highlighted), partially offsetting the impact of key product lines being at the end of cycle
|
- Strong performance in apparel, albeit a smaller proportion of our category mix in North America
|
- Much improved overall online performance, supported by a better online range and focused marketing
|
- Continuing to manage the conversion to JD of the Finish Line fascia, where market-driven promotional intensity remains higher than normal in the short term
|
- Pricing and gross margin % are wellwell-managedd overall
|
| Europe & UK(4) (34% and 26% of Q2 sales, respectively) |
- Both regions had tough comparatives from: (i) last year's Euro 2024 football tournament (replica kit and in-store cross-sell) and (ii) athletic footwear for women
|
- Resilient underlying performance in apparel, supported by a strong product offer
|
- Footwear performance in both regions is supported by newer footwear lines (especially performance-based) and value-oriented footwear, against tough comparatives, especially in footwear for women and juniors
|
- Maintained in-store pricing disciplines in both regions. Controlled price investments in the online offer to boost competitiveness and increase engagement with online customers. Reflected in higher European online traffic and conversion in Q2
|
| H1 Group gross margin % MOVEMENT: |
- Excluding Hibbett and Courir (businesses acquired in FY25), gross margin % for the Group in H1 was 40bps lower YoY. This was largely driven by controlled price investments in the online offer
|
- Including acquisitions, the overall gross margin % in H1 was 60bps lower YoY
|
- Inventory levels at the end of H1 were in line with our expectations, and continue to be managed effectively
|
| OUTLOOK AND GUIDANCE(5): |
- On overall trading conditions through H2, we remain cautious given the continued strains on consumer finances, unemployment risk, and the ongoing shift in the footwear product cycle
|
- We expect to be in line with current market expectations(2,3) for FY26 profit before tax and adjusting items (PBTAI), albeit we continue to assess the potential impacts from US tariffs
|
- US tariffs: As a reminder, we do not consider the direct impacts of US tariffs on JD to be material. On indirect impacts, we continue to monitor the ever-changing landscape of tariffs, keeping in close contact with our brand partners on how they are addressing the situation. We'll provide a further update within our H1 results on 24 September
|
- Profit phasing H1/H2: Historically, we have generated more of our profits in H2, owing to seasonality within the business. In FY26, H2 is likely to represent c.60% of our PBTAI, including the impact of:
|
-
- An expected mark-to-market (non-cash) net charge of c.£14m in H1, mainly related to the revaluation of open FX hedging contracts as of 2 August 2025
|
-
- The expected benefit in H2 from US (Hibbett) synergies is starting to come through
|
| REFINANCING AND SHAREHOLDER RETURNS: |
- Refinancing: In early July, JD Group completed a comprehensive refinancing of its debt facilities, securing a new 5-year £1bn multi-bank revolving credit facility and associated 3-year US$700m term loan
|
- Strong free cash flow; new £100m share buyback programme: In line with our capital allocation policy and reflecting our strong free cash flow generation, the Board has determined that surplus capital is available for return to shareholders. Further to the ordinary dividend and the recently completed £100m share buyback programme (as announced on 28 July 2025), the Board is pleased to announce the return of a further £100m via a share buyback programme. The Board has selected this mechanism of returning surplus capital as they believe it represents a compelling return on equity given JD's current share price levels. We expect to commence the programme post the announcement of our H1 results on 24 September.
|
| For the full document, click the link below |
| JD Sports Fashion PLC |
| Stay ahead of the curve! Subscribe to InsidEntity for daily updates on all your favourite companies. |